Dollar Rally Pauses On Soft Data
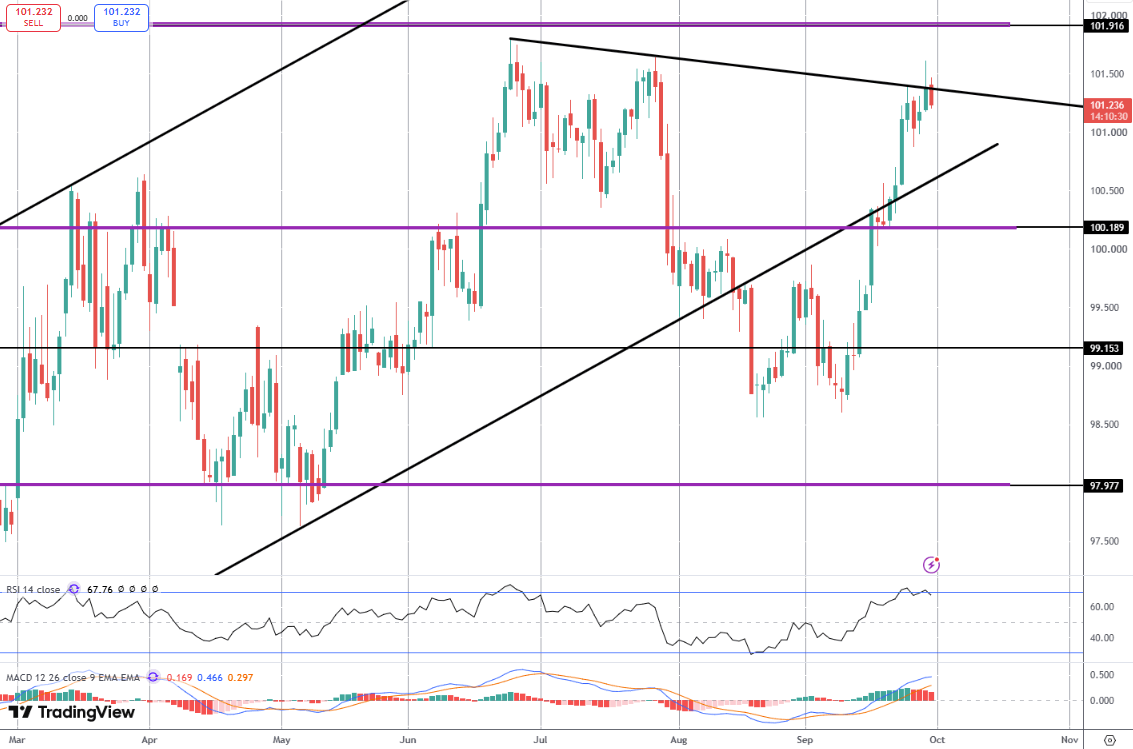
DXY Stalls
The US Dollar is lower today amidst a downturn in Fed rate hike expectations on the back of softer US data yesterday. Weak US consumer sentiment and JOLTS job openings numbers saw market pricing for an October hike plunge to around 50% from above 70% prior. The reaction shows just how sensitive rate-hike expectations are to incoming data.
US Data on Watch
Focus now turns to today’s readings with the ADP jobs number, final quarterly GDP reading and core PCE all due. Any further weakness today should see market pricing dipping firmly back under the 50% level fuelling a covering of recent USD longs into Friday’s headline NFP release. In particular today, the ADP print will be closely watched (often used as a gauge for the NFP number), especially given the drop in JOLTS data seen yesterday.
Jobs Data Key
If today’s ADP release is soft (exp 73k vs 38k prior), this could strengthen the view that Friday’s data is likely to be soft also, fuelling heavier long covering ahead of that release. On the other hand, if today’s three key readings come in strong, we should see October hike pricing rebounding and USD turning higher into Friday’s data accordingly. A such, plenty of volatility risk in USD today and into Friday’s headline NFP release.
Technical Views
DXY
The rally in the index has stalled for now into a test of the bear trend line from the YTD highs. With momentum studies still bearish and price still within the bull channel, focus is on a continuation higher towards the YTD highs and 101.91 level next. Only a shift below the 100 level would negate this view, turning focus to 9..15 as the next bear target.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% and 73% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
With 10 years of experience as a private trader and professional market analyst under his belt, James has carved out an impressive industry reputation. Able to both dissect and explain the key fundamental developments in the market, he communicates their importance and relevance in a succinct and straight forward manner.